Anthropic's entry into the public stock market has created one of the biggest investment stories of 2026. The company behind Claude completed its initial public offering (IPO) on November 19, raising approximately $93.5 billion after the full exercise of the underwriters' additional share option. Its Class A common stock trades on the Nasdaq Global Select Market under the ticker symbol ANT.
The IPO priced shares at $83, valuing Anthropic at approximately $1.5 trillion on a fully diluted basis. However, the company's first two trading sessions have already shown that strong investor demand does not guarantee a steadily rising share price. After closing at $97.17 on November 19, Anthropic shares fell to $88.91 on November 20. The market's initial enthusiasm is now being tested against the company's financial performance, infrastructure obligations and long-term profitability prospects. With revenue growing rapidly but significant financial risks remaining, investors face a central question: Is Anthropic stock a rational investment at its current valuation?
Anthropic's $93.5 Billion IPO Puts AI Investment in the Spotlight
Anthropic priced its IPO at $83 per share, above its initial marketed range of $70 to $78. Trading began on November 19, 2026, with shares opening at $111.50. The company initially offered 980 million Class A shares. On November 20, Anthropic confirmed that the underwriters had exercised their full option to purchase an additional 147 million shares. This increased the total offering to 1.127 billion shares and brought gross IPO proceeds to approximately $93.5 billion. Anthropic received approximately $91.6 billion, while the remainder went to selling shareholders.
The company also completed a separate $26 billion private placement involving strategic investors, including Google, Microsoft, NVIDIA, AMD, Broadcom, Micron and TSMC Partners. Combined gross proceeds from the IPO and private placement reached approximately $119.5 billion before expenses. The IPO's scale is significant because it gives Anthropic substantial capital to support its AI research, infrastructure requirements and business expansion.
How Has Anthropic Stock Performed Since Listing?
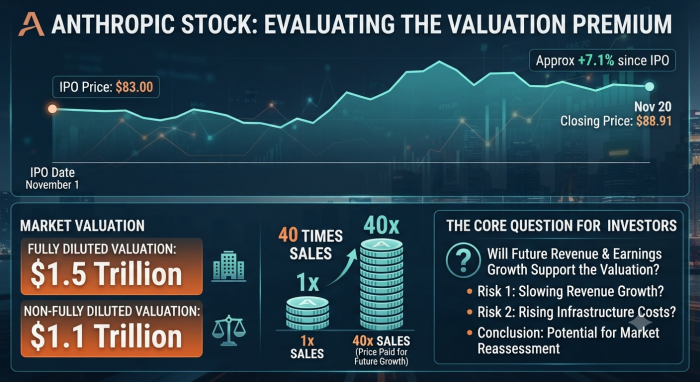
Anthropic's initial trading performance has been volatile. Shares opened at $111.50 on November 19 and closed at $97.17, approximately 17.1% above the IPO price. However, the stock lost ground during the following session, closing at $88.91 on November 20.
| Stock market metric | Price |
|---|---|
| IPO price | $83.00 |
| November 19 opening | $111.50 |
| November 19 closing | $97.17 |
| November 20 closing | $88.91 |
| Gain over IPO price at November 20 close | 7.1% |
| November 20 daily change | -8.5% |
The decline came during a broader technology market sell-off. Reuters reported that NVIDIA shares also fell approximately 14% during the same period, reflecting investor concerns about the scale of AI infrastructure spending and the returns expected from the technology sector. Another important development was the exercise of the full 147-million-share greenshoe option. Reuters reported that this removed the underwriter's remaining share-stabilisation buying mechanism, potentially leaving the stock more exposed to market volatility. Despite the decline, ANT shares remained above their original offering price at the November 20 close.
Anthropic's Financial Results: Revenue Is Growing Rapidly
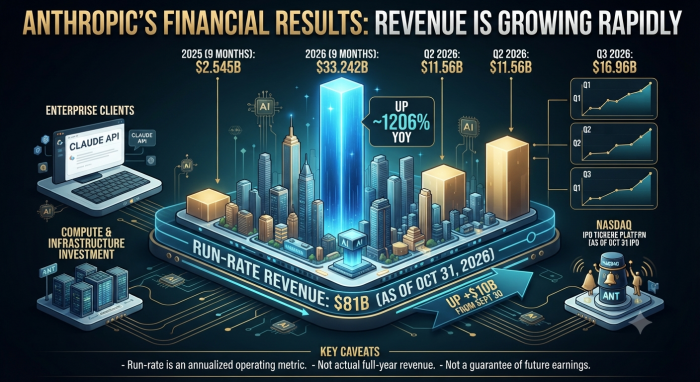
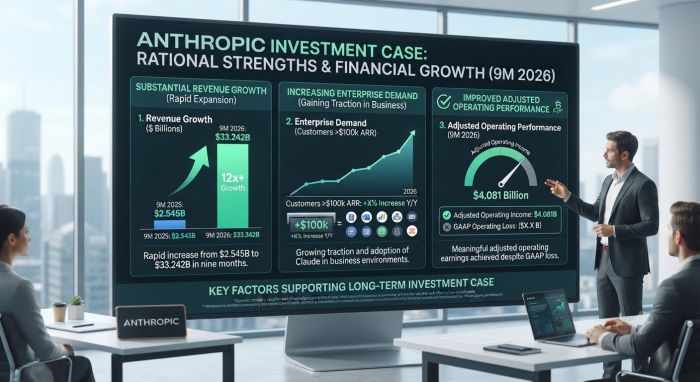
The strongest argument supporting Anthropic's valuation is its revenue growth. According to its final SEC prospectus, the company generated $33.242 billion in revenue during the nine months ended September 30, 2026, compared with $2.545 billion during the same period in 2025. That represents year-over-year growth of approximately 1,206%. Its third-quarter revenue reached $16.96 billion, compared with $11.56 billion in the second quarter. Anthropic also reported an approximately $81 billion revenue run rate as of October 31, 2026, up $10 billion from September 30.
However, this figure is an annualized operating metric based on recent consumption and subscription activity. It is not actual full-year revenue or a guarantee of future earnings.
Anthropic's Latest Financial Figures
| Financial metric | Reported figure |
|---|---|
| 2025 annual revenue | $4.585 billion |
| Nine-month 2025 revenue | $2.545 billion |
| Nine-month 2026 revenue | $33.242 billion |
| Q2 2026 revenue | $11.56 billion |
| Q3 2026 revenue | $16.96 billion |
| October 2026 annualized revenue run rate | Approximately $81 billion |
| Nine-month 2026 GAAP operating loss | $1.26 billion |
| Nine-month 2026 adjusted operating income | $4.081 billion |
| Nine-month 2026 net loss | Approximately $104.04 billion |
These results reveal an important distinction between Anthropic's reported accounting performance and its adjusted operating performance. The company reported a $1.26 billion GAAP operating loss for the first nine months of 2026. However, its adjusted operating income was approximately $4.081 billion, with an adjusted operating margin of approximately 12%. The company also reported a net loss of approximately $104.04 billion. This exceptionally large net loss included approximately $94.3 billion in changes in the fair value of convertible notes, derivative liabilities and SAFEs. These were primarily non-cash accounting adjustments associated with changes in the company's valuation.
Consequently, the $104.04 billion figure should not be interpreted as an equivalent cash operating loss. Nevertheless, investors should not ignore the GAAP operating loss or assume that adjusted operating income represents cash generated by the business.
Is Anthropic Stock Overvalued at Its Current Price?
Valuation is arguably the most important issue for investors considering Anthropic shares. At its $83 IPO price, the company carried an approximately $1.5 trillion fully diluted valuation. Its non-fully diluted valuation was approximately $1.1 trillion. Reuters described Anthropic's valuation as approximately 40 times sales, indicating that investors are paying a substantial premium for its expected future growth. This valuation reflects expectations that Anthropic will continue expanding its enterprise customer base, increasing Claude adoption and generating revenue from advanced AI applications. However, high revenue growth does not automatically justify a high stock valuation.
The company's $81 billion annualized revenue run rate provides an indication of its recent commercial momentum, but it should not be confused with reported annual revenue. The calculation also relies on short measurement periods, which Anthropic itself warns may not accurately predict future results. At the November 20 closing price of $88.91, the stock was approximately 7.1% above its IPO price. Its market valuation therefore remained elevated despite the post-listing decline. For investors, the key question is whether future revenue and earnings growth will be sufficient to support the valuation. If revenue growth slows or infrastructure costs rise faster than expected, the market could reassess the premium currently attached to the stock.
The $900.9 Billion Infrastructure Commitment Behind Anthropic's Growth
One of the most significant risks in Anthropic's SEC prospectus is its long-term infrastructure spending. As of and subsequent to September 30, 2026, the company reported approximately $900.9 billion in aggregate committed spending under purchase commitments and lease agreements.
According to the filing:
Approximately $451.6 billion is expected to be incurred before December 31, 2030.
Approximately $70.7 billion is due during the 12 months following September 30, 2026.
Most of the remaining commitments are expected between 2031 and 2045.
These commitments are substantially related to computing capacity and infrastructure required to develop, train and operate advanced AI systems. Importantly, the $900.9 billion figure is not money Anthropic has already spent or borrowed. It represents contractual commitments, including leases and arrangements that may be subject to termination rights or other conditions. The prospectus also identifies approximately $150 billion to $175 billion in additional estimated payments under certain arrangements without fixed dollar commitments.
This scale of infrastructure spending is central to the investment debate. Anthropic needs access to computing resources to maintain its competitive position, but those resources also create significant long-term financial obligations.
Why Claude's Enterprise Business Matters to Investors
Anthropic's investment case is closely connected to the commercial adoption of Claude. Its prospectus reported more than 11,900 customers generating at least $100,000 in trailing 12-month revenue as of September 30, 2026, compared with more than 950 customers a year earlier. Revenue from this customer group reached approximately $24.5 billion during the first nine months of 2026.
Claude Code has also become an important part of the company's commercial growth, particularly among software developers using AI to write, review and manage code. This enterprise demand matters because it provides a broader revenue base than individual chatbot subscriptions alone. However, the sustainability of this growth remains an important question. Anthropic's prospectus acknowledges that early customer adoption and rapid expansion may not continue at the same rate as the business becomes larger.
What Could Make Anthropic Stock a Rational Investment?
Anthropic has three particularly important financial and commercial strengths.
- First, its revenue growth is substantial. The increase from $2.545 billion to $33.242 billion in nine-month revenue demonstrates rapid commercial expansion.
- Second, enterprise demand is increasing. The growth in customers generating at least $100,000 in annual revenue suggests that Claude is gaining traction in business environments.
- Third, adjusted operating performance has improved. The $4.081 billion adjusted operating income reported for the first nine months of 2026 indicates that the company has developed meaningful adjusted operating earnings despite its GAAP operating loss.
These factors provide a basis for the company's long-term investment case. However, they must be considered alongside its valuation and infrastructure commitments.
What Could Make Anthropic Stock a Risky Investment?
The most important concerns are its high valuation, significant computing commitments and uncertain GAAP profitability. Anthropic is competing with OpenAI, Google and other major AI developers that have substantial resources and established technology ecosystems. A decline in demand for Claude, more competitive pricing from rivals or slower adoption of AI products could affect its revenue growth. Its infrastructure commitments also create execution risks. Delays in data-centre construction, financing, hardware availability or energy supply could affect its ability to meet customer demand.
There is also a corporate governance consideration. Anthropic is structured as a Delaware public benefit corporation. Its governance arrangements give the Long-Term Benefit Trust a role in electing and removing a majority of its board through its designated Class T directors. Its founders' Class F shares also carry 50.1% of the general voting power. This means public shareholders do not have the same level of governance influence they might expect from a conventional publicly traded company.
Is Anthropic Stock a Rational Investment in November 2026?
Anthropic's financial disclosures provide a stronger basis for evaluating its stock than the excitement surrounding its IPO alone. The company has reported exceptional revenue growth, a rapidly expanding base of high-value customers and positive adjusted operating income. These are meaningful strengths.
However, its approximately $1.5 trillion fully diluted IPO valuation, $900.9 billion in infrastructure commitments and continuing GAAP operating losses create significant investment risks. The November 20 share-price decline also demonstrated that investors are already questioning how much future growth is reflected in the stock price. For investors considering ANT, the important indicators will be future reported revenue, GAAP operating margins, cash flow, infrastructure spending and the company's ability to convert its adjusted earnings into sustainable financial performance.
At this stage, Anthropic represents a major public-market opportunity in the AI industry, but its high valuation means that strong future execution is essential to justify the price. The central investment question is no longer whether Anthropic can attract demand for Claude. It is whether the company can convert that demand into sustainable profits while meeting the enormous infrastructure commitments required to compete in the next phase of AI.
Comments